
Who is who in payments: store, bank, network and processor
Photo: Avila Ops Tecnologia
Four parties participate in online card purchases: the store, you; the customer’s bank, which issued the card; the network, Visa, Mastercard or Elo, providing rules and infrastructure; and the payment processor, connecting your store and depositing into your account. Each does a job and charges for it.
When something fails, know whom to call. Declines usually come from the customer’s bank, sometimes processor fraud screening. Missing funds require the processor. Bank-forced refunds, chargebacks, pass through the network.
What does each do during purchase?
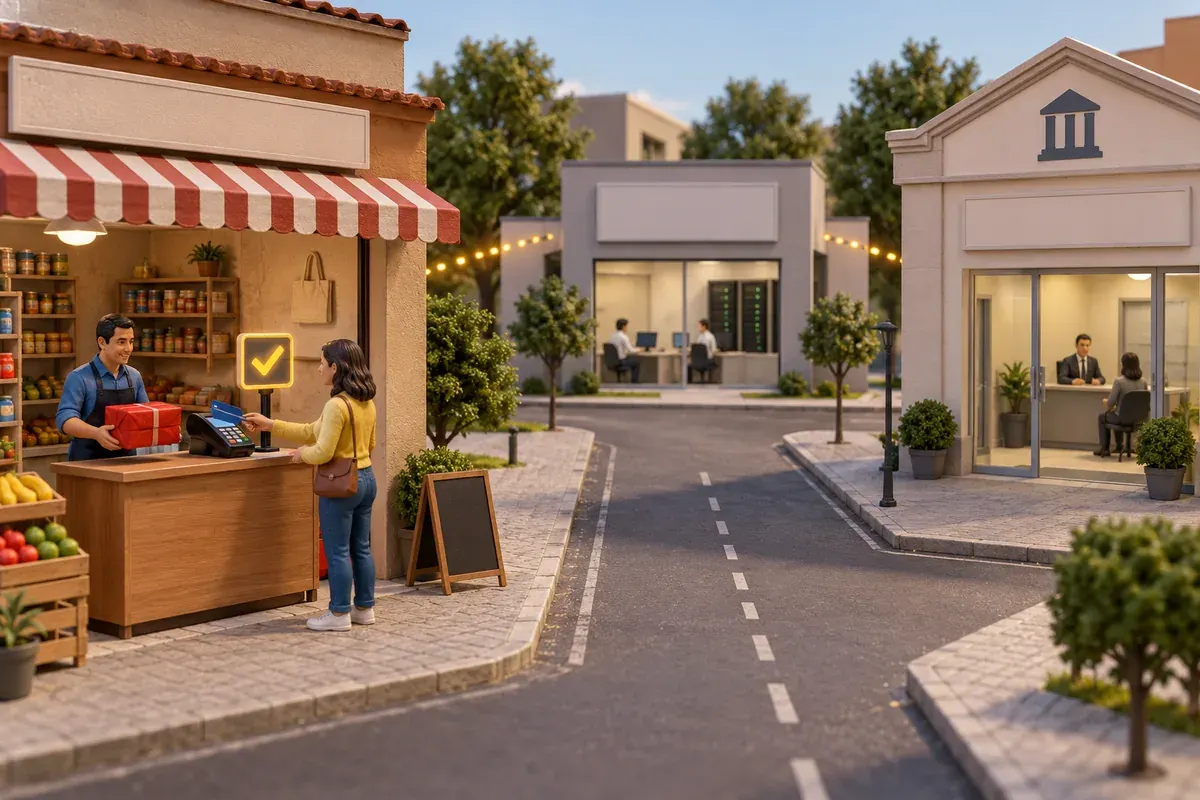
Photo: Avila Ops Tecnologia
Within seconds:
- Customers enter card details at checkout.
- The processor, Mercado Pago, PagSeguro, Pagar.me or others, receives data, screens fraud and requests authorization through the acquirer.
- The network takes the request to the customer’s bank.
- The bank checks limit, password and fraud, responding approved or denied.
- The response returns along the same route and your store marks the order paid.
You do not have the money yet. For credit, the bank pays the acquirer about 30 days later; the acquirer transfers to the processor, which deposits under your contract. Installments arrive all at once or separately depending on the contract. See Settlement time: why card payments take time. Pix has no card network: Brazil’s Central Bank maintains the network and money arrives instantly.
Who charges what?
The customer’s bank keeps an interchange fee. The network charges for network use. Acquirer and processor add their portions, and you pay one percentage including everything.
Store platforms may add commission; Avila Ops does not. Processor fees remain according to their contracts. See What payment processors are and what they charge.
What to do now
Open the processor statement and separate sale amount, deducted fee and deposit date. If you cannot see all three, you are in the wrong place. Instant Pix, cards and boleto without platform commission: avilaops.com/loja-virtual or contact us on WhatsApp: wa.me/5517997811471.
Frequently asked questions
Are acquirers and processors the same?
Almost. Acquirers such as Cielo, Rede and Stone contract directly with networks and settle sales. Processors, or subacquirers, use an acquirer’s infrastructure and simplify small-store registration. Mercado Pago and PagSeguro now perform both roles. For you, the result is one fee and deadline.
Do I need a particular bank account?
No. Processors deposit to any account in the registered holder’s name. Use the business account to separate personal money.
Who is responsible for declined cards?
Usually the customer’s bank, sometimes processor fraud screening. Stores receive “denied,” usually without a reason. Suggest another card or Pix.
Turn what you learned into your next step.
Tell us about your company and what you want to improve. We can explore the right tools, integrations or custom project together.